Kalshi vs Robinhood Prediction Markets: Fees, Markets and Availability
Kalshi and Robinhood both let eligible customers trade event contracts, but they do not always represent two separate markets. Kalshi is a CFTC-designated contract market that lists contracts and operates an exchange. Robinhood Derivatives is a futures commission merchant, or FCM, that gives customers access to contracts listed by partner exchanges—including KalshiEX for some products.
That structure changes how a fair comparison works. A Robinhood quote can come from Kalshi, ForecastEx, Rothera Exchange and Clearing, or North American Derivatives Exchange, also known as CDNA. Before comparing price, liquidity or settlement, identify the listing venue. Otherwise, you may compare direct Kalshi access with an intermediated route to the same Kalshi market.
Our verdict: Kalshi is the stronger default for direct exchange access, desktop and web trading, public market data, API workflows and broader international eligibility. Robinhood is the stronger fit for an eligible US brokerage customer who values one mobile app, automatic movement of buying power and multi-leg combinations. Neither is always cheaper or more liquid. The contract, venue, executable price, available size and full fee preview decide the better order.
Last reviewed and fact-checked: October 30, 2026.
Editorial disclosure: Macro Markets publishes this comparison and operates a prediction-market platform. We include Macro Markets as a disclosed crypto-native alternative, apply the same decision criteria and do not present it as a CFTC-designated US exchange. This is a documentation-based comparison; we did not open, fund and place simultaneous matched orders through Kalshi and Robinhood. Event contracts are speculative and can lose the full amount committed. This page is educational, not financial, legal or tax advice.
Kalshi vs Robinhood Prediction Markets: Quick Verdict
Choose Kalshi when you want to trade on the exchange directly. Its native experience exposes order books, supports resting limit orders, works on web and mobile, and offers an API for market data and account workflows. Kalshi also accepts eligible users from the United States and many other jurisdictions, subject to its restricted-country list, identity checks and local law.
Choose Robinhood when you already use its brokerage ecosystem and want event contracts inside the same mobile app. Robinhood Derivatives can provide one customer relationship across several exchanges, supports immediate-or-cancel and good-till-date limit orders, and offers preset or custom combinations of up to ten legs when supported. Buying power can move automatically between the brokerage and event-contract accounts.
The choice is not simply “exchange A versus exchange B.” It is often:
- Kalshi direct: customer → KalshiEX order book → Kalshi contract and settlement rules.
- Robinhood route: customer → Robinhood Derivatives FCM → the exchange named on that contract.
- Possible overlap: if Robinhood names KalshiEX as the venue, both routes ultimately reach a Kalshi-listed contract.
Winner by use case
- Direct exchange relationship: Kalshi.
- Web and desktop execution: Kalshi; Robinhood currently limits prediction-market trading to its mobile app.
- Public API and technical workflow: Kalshi.
- One-app brokerage convenience: Robinhood.
- Multi-exchange discovery through one intermediary: Robinhood.
- Custom combinations: Robinhood, where an exchange quote is available.
- International eligibility: Kalshi, subject to jurisdictional restrictions.
- Lower fee in the matched 100-contract, 50-cent illustration: Kalshi by as much as $0.25 under the schedules described below.
- Best liquidity: no universal winner without matched venue, contract, time and quantity evidence.
- Crypto-native funding and global discovery: Macro Markets for eligible users, with a different jurisdiction, custody and regulatory profile.
Our prediction-market comparison methodology explains why the listing venue and executable order matter more than brand-level claims. For deeper individual analysis, read the Kalshi review and Robinhood prediction markets review.
Kalshi vs Robinhood at a Glance
| Decision factor | Kalshi | Robinhood Prediction Markets | Practical edge |
|---|---|---|---|
| Customer route | Direct exchange account with KalshiEX | FCM account routing to supported exchanges | Depends on preferred account structure |
| Possible listing venues | KalshiEX | KalshiEX, ForecastEx, Rothera or CDNA, depending on contract | Robinhood for venue breadth; Kalshi for directness |
| Minimum age | 18+, subject to eligibility | 18+, US resident with approved individual account | Similar baseline |
| Geography | United States and many international jurisdictions; restrictions apply | United States only; state and contract restrictions apply | Kalshi |
| Trading surface | Web and mobile, plus API | Mobile app for execution; view-only on web; unavailable on Legend | Kalshi |
| Orders | Marketable and resting limit orders, order book controls | IOC, GTD limit and dollar orders; some fractional closing trades | Kalshi for book control; Robinhood for familiar app flow |
| Combinations | Contract and product dependent | Preset and custom combinations up to ten legs, when quoted | Robinhood |
| 100 contracts at 50 cents | $1.75 under Kalshi's July 2026 general immediately matched schedule | Up to $2 total: $1 Robinhood commission plus up to $1 exchange fee | Kalshi in this narrow example |
| Funding | Dedicated exchange funding rails | Separate event buying power with automatic brokerage sweeps | Robinhood for existing account convenience |
| Settlement | Kalshi contract rule and named source | Listing exchange's contract rule and named source | Read the exact contract |
| Liquidity | Contract-, side- and time-specific | Comes from the named exchange and contract | No universal winner |
The most important row is the venue
Suppose the same election contract appears in both apps. If the Robinhood order ticket identifies KalshiEX, both products can reference the same underlying exchange market. The displayed price can still differ momentarily because of refresh timing, order type, quantity, fees or interface behavior, but it is not evidence of two independent liquidity pools.
If Robinhood instead identifies ForecastEx, Rothera or CDNA, the contracts may look similar while using different deadlines, official sources, thresholds or exceptional-outcome rules. Match the complete specification before comparing prices.
Platform fit versus contract fit
A convenient platform can still show an unattractive contract. Separate two decisions:
- Platform fit: eligibility, account structure, funding, interface, controls and support.
- Contract fit: exchange, source, deadline, price, spread, depth and settlement terms.
The platform determines how you access the trade. The listing exchange and written contract determine what you own and how it resolves.
What the table cannot establish
The table cannot prove a permanent liquidity winner. It also cannot show the price available for your full quantity when you submit an order. Last trade, midpoint and displayed probability are not guarantees of execution.
Compare the bid, ask, available quantity and fee preview at the same time. A one-cent worse execution across 100 contracts costs $1—more than the 25-cent maximum difference in the matched fee example below.
Regulation, Exchange Routing and Account Structure
Kalshi and Robinhood occupy different layers of regulated US derivatives infrastructure. Understanding those roles prevents several common errors about safety, liquidity and settlement.
Kalshi as the listing exchange
The CFTC's Kalshi record identifies KalshiEX as a designated contract market. Kalshi lists event contracts, operates the marketplace and publishes the rules that define each outcome. Its affiliated clearing infrastructure processes positions and settlement.
A retail customer using Kalshi directly has a relatively short route: account, order book, contract rule and settlement source all sit within the Kalshi exchange relationship. That does not guarantee a fill, a narrow spread or a profitable forecast. It does make the venue identity explicit.
Kalshi can also support intermediated access. Its DCM status does not mean every customer must arrive only through Kalshi's native interface. Robinhood can be one intermediary for selected Kalshi-listed contracts.
Robinhood Derivatives as the FCM
Robinhood Derivatives, LLC is a CFTC-registered FCM and an NFA member. An FCM carries the customer relationship, accepts orders and facilitates access to designated contract markets. It is not automatically the exchange that created or listed the contract.
Robinhood's official event-contract overview identifies four possible venues as of this review:
- KalshiEX LLC;
- ForecastEx, LLC;
- Rothera Exchange and Clearing LLC; and
- North American Derivatives Exchange, Inc., which Robinhood abbreviates as CDNA.
The specific order ticket should name the exchange. That name controls which rulebook, market operator and settlement source apply. Robinhood provides the access layer and commission schedule, but it says the listing exchange—not Robinhood—decides whether the event occurred under the contract terms.
Direct and intermediated routes in one picture
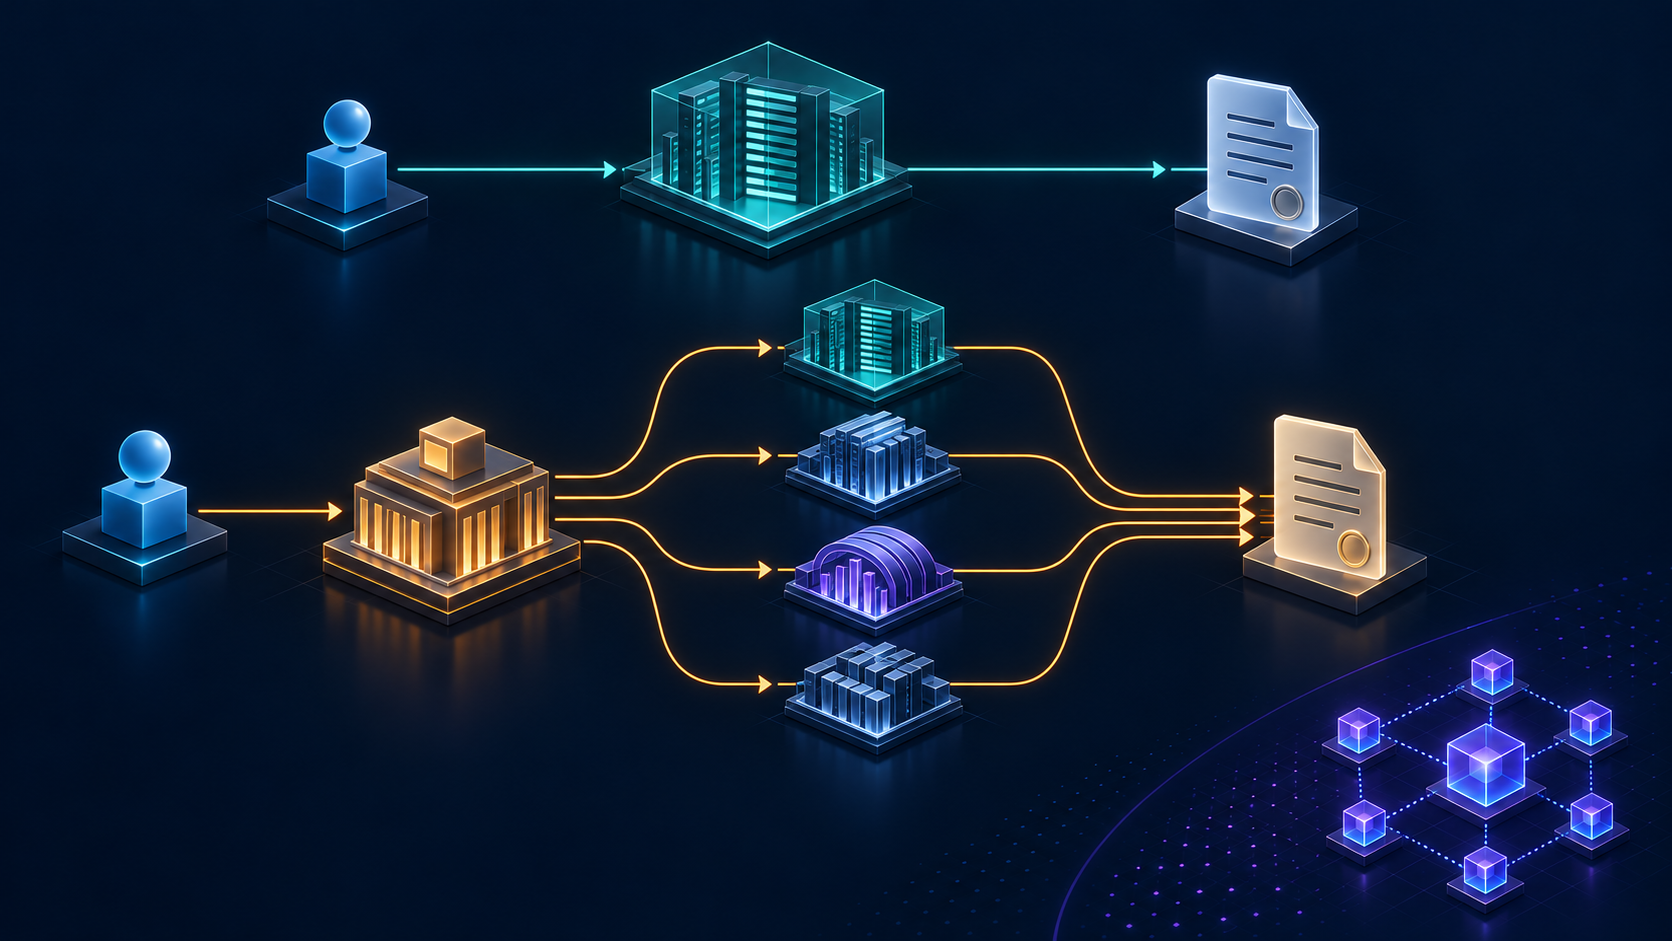
The upper route shows a customer entering Kalshi directly. The lower route shows a customer entering through Robinhood Derivatives and then reaching the exchange identified on the contract. One branch can lead to KalshiEX, which is why a venue check must come before any claim that the two products show separate markets.
Does Robinhood use Kalshi?
Yes, for some contracts. That answer should not be expanded into “every Robinhood event contract is a Kalshi contract.” Robinhood supports multiple venues, and the catalog can change. Check the exchange disclosure on the order preview and the contract details.
This distinction matters in three ways:
- Liquidity: orders ultimately depend on the named exchange's market and available counterparties.
- Rules: the named exchange defines the official source, observation window and exceptional outcomes.
- Fees: Robinhood can charge its commission while the exchange can charge a separate fee.
What regulation does and does not mean
CFTC registration and NFA membership provide important information about legal roles, disclosures and supervision. They do not insure a forecast against loss, guarantee that a position can be sold early or make every sports-related contract available in every state.
Robinhood states that its derivatives business is not SIPC protected or FDIC insured. Kalshi event contracts are also speculative products, not bank deposits. A fully collateralized binary position can still lose its entire purchase price plus applicable fees.
Federal exchange regulation and state access are separate issues. Our guide to whether prediction markets are legal explains why location restrictions can remain even when a DCM or FCM is federally registered.
Fees, Spreads and a 100-Contract Cost Example
A defensible fee comparison separates four layers: contract premium, Robinhood commission, exchange fee and market friction. Robinhood Gold is a fifth cost if the subscription is maintained for reasons related to trading.
Kalshi fee snapshot
Kalshi's general schedule effective July 7, 2026 uses a probability-weighted fee for orders that immediately match resting liquidity:
fee = round up(M × 0.07 × C × P × (1 − P))
P is the contract price in dollars, C is the number of contracts and M is the series multiplier. Special series, maker treatment and promotions can differ. The live order ticket and current fee schedule control.
At $0.50 with a multiplier of one, 100 immediately matched contracts carry a published general fee of $1.75. Fees generally decline as the price approaches either extreme because the probability-weighted term becomes smaller.
Robinhood's current commission formula
For orders placed from June 1, 2026, Robinhood documents this commission:
Robinhood commission = k × P × (1 − P) × C
The coefficient k is 5% for Robinhood Gold customers and 10% without Gold. Robinhood rounds the aggregate commission up to the nearest cent and caps it at $0.01 per contract. Gold itself currently carries a separate monthly subscription cost, which should not be hidden inside a favorable trading example.
The listing exchange can add its own fee, varying by venue and contract, of up to $0.01 per contract under Robinhood's current disclosure. Therefore, “Robinhood charges one cent” can be incomplete: one cent may describe the capped Robinhood commission, while another exchange fee may apply.
A matched 100-contract example at 50 cents
Assume economically identical Yes contracts, the same exchange-quality execution at $0.50 and sufficient size for 100 contracts.
| Cost component | Kalshi direct | Robinhood Gold | Robinhood without Gold |
|---|---|---|---|
| Contract premium | $50.00 | $50.00 | $50.00 |
| Platform commission | $1.75 Kalshi fee | $1.00 after per-contract cap | $1.00 after per-contract cap |
| Possible separate exchange fee | Included in the direct Kalshi schedule used here | Up to $1.00 | Up to $1.00 |
| Entry total before spread/funding | $51.75 | Up to $52.00 | Up to $52.00 |
Kalshi is up to $0.25 cheaper in this narrow illustration. Gold does not reduce the Robinhood commission at 50 cents because both coefficients reach the one-cent-per-contract cap for 100 contracts. Paying for Gold solely to improve this particular fee would therefore produce no commission benefit.
A 90-cent example shows where Gold can matter
At $0.90 for 100 contracts, the probability term is smaller:
- Robinhood Gold commission:
0.05 × 0.90 × 0.10 × 100 = $0.45. - Robinhood non-Gold commission:
0.10 × 0.90 × 0.10 × 100 = $0.90. - A separate exchange fee may still apply to either account.
The 45-cent commission difference is real, but it should be compared with the subscription price, trading frequency and other Gold benefits. It does not prove that the Gold order has a better quote or lower all-in cost.
Spread, slippage and early exit
Explicit fees are only one component. The full entry cost is:
premium + commission + exchange fee + spread + slippage + funding cost
An early sale can add another commission, another exchange fee and a second encounter with the spread. A position may be impossible to close at an acceptable price if there are no buyers. In that case, the customer may have to hold until settlement.
Use the prediction-market fee calculator to model these layers. Our explanation of the bid-ask spread shows why a displayed probability is not the same thing as an executable price.
The correct price-comparison sequence
For a contract offered through Robinhood and directly on Kalshi:
- Confirm whether Robinhood names KalshiEX or another exchange.
- Match the side, rules, deadline and full quantity.
- Compare executable prices at the same timestamp.
- Add Kalshi's direct fee or Robinhood's commission plus exchange fee.
- Model a potential exit rather than assuming settlement is the only outcome.
If both routes name KalshiEX, a transient screen difference may reflect timing or presentation rather than a durable arbitrage opportunity.
Markets, Availability, Funding and Trading Tools
Both products cover sports and non-sports events. The larger differences are geography, trading surface, account funding and the level of direct market control.
Market catalogs
Kalshi lists sports, politics, economics, weather, crypto, technology, entertainment and culture contracts. Its catalog is organized as a dedicated event exchange, which suits traders who routinely move across forecasting categories.
Robinhood offers sports, politics, weather, commodities and entertainment through supported exchanges. Because several exchanges can sit behind the app, availability and contract design can vary. A category visible today is not a commitment that the same venue, fee or contract will be available later.
Robinhood's venue breadth can be useful: one approved account may expose listings from several exchanges. The trade-off is more diligence per order. “Available on Robinhood” does not identify who operates the market.
US, international and state availability
Kalshi's published baseline is age 18 or older and it accepts applications from the United States and many international jurisdictions, subject to verification, restricted countries and local law. Access to individual contracts can still be limited.
Robinhood requires an approved Robinhood Derivatives account connected to an eligible individual brokerage account. The customer must be at least 18, have a US residential address and be a US citizen, permanent resident or valid visa holder under Robinhood's current criteria.
State restrictions are dynamic. As of this fact check, Robinhood's official materials identify Maryland as unavailable for event contracts and impose restrictions on opening new sports contracts in Nevada and Michigan. Additional exchange, category or account controls can apply. The app's current eligibility message should override a dated article.
Funding and buying power
Kalshi uses a dedicated exchange balance and supports several funding rails depending on location and direction. Processing fees, deposit limits and settlement times vary by method.
Robinhood maintains event-contract buying power separately from brokerage and crypto balances, but the system can sweep eligible funds automatically. That is convenient for an existing customer because a manual transfer may not be required before each order.
Convenience does not make all cash immediately usable. Robinhood says Instant Deposits may be unavailable for event contracts. When settled cash is required, a bank transfer can take one to five business days. Plan funding before a time-sensitive market reaches its close.
Trading surface and order types
Kalshi supports trading through web and mobile interfaces and provides public API documentation. Its exchange-native tools are the stronger fit for users who want visible book data, resting orders, programmatic monitoring or systematic execution.
Robinhood's official event-contract trading guide currently limits prediction-market execution to its mobile app. Customers can view markets on the web, but cannot trade there, and the product is not available in Robinhood Legend. That is a meaningful limitation for desktop-first traders.
Robinhood does support more than simple market orders:
- IOC limit orders execute immediately at the limit or better and cancel any unfilled portion.
- GTD limit orders can rest until filled or expire at 3:00 a.m. ET on the next calendar day under the current support description.
- Dollar orders are handled as immediate-or-cancel orders.
- Fractional closing trades are available in some markets where sub-penny trading is supported.
Robinhood also supports preset and custom combinations of up to ten legs. Combo orders use fill-or-kill behavior and require the exchange to return a quote or find a counterparty. A requested combination is not guaranteed to execute.
Liquidity, API and settlement
Kalshi is the clearer choice for public data and API-based workflows. Robinhood's consumer product is not positioned as an open retail event-contract execution API. Developers should not assume that an API for stocks or brokerage data grants comparable prediction-market order access.
Neither brand has permanent control over liquidity in every comparison. On Robinhood, liquidity belongs to the named exchange and specific contract. On Kalshi direct, it belongs to the Kalshi market. Compare executable size, not total company volume or app popularity.
Robinhood does not decide the outcome of a partner exchange's contract. The exchange's rule, official source and timing control settlement. Read those terms before entering, especially for postponed sports events, revised data releases, recounts or ambiguous entertainment outcomes. Our guide to how to trade on prediction markets includes a pre-order checklist.
A crypto-native alternative
Macro Markets is a disclosed crypto-native alternative for eligible users who prioritize crypto funding and global market discovery. Its product direction is built around crypto rails rather than a US brokerage account or direct access to a CFTC-designated exchange.
That difference creates another diligence list: jurisdiction, eligibility, collateral asset, wallet and custody flow, network costs, withdrawal mechanics, liquidity and resolution. Macro Markets is not presented here as a CFTC-designated US exchange, and its regulatory and custody profile should not be treated as equivalent to Kalshi or Robinhood Derivatives.
Because Macro Markets publishes this article, verify its current terms independently. For a broader shortlist, see the best prediction market apps and Kalshi alternatives.
Frequently Asked Questions
Is Kalshi better than Robinhood for prediction markets?
Kalshi is better for direct exchange access, web trading, visible order books, API workflows and international eligibility. Robinhood is better for eligible US customers who prioritize a familiar mobile brokerage account, automatic buying-power sweeps and multi-leg combinations.
Does Robinhood use Kalshi?
Robinhood can offer contracts listed by KalshiEX. It can also offer contracts from ForecastEx, Rothera and CDNA. Check the exchange named on the specific order; not every Robinhood event contract comes from Kalshi.
Is Robinhood a prediction-market exchange?
Robinhood Derivatives is an FCM, not the listing exchange for every contract. It carries the customer account and routes orders to supported exchanges. The named exchange operates the market and controls the contract rules and settlement.
Are Kalshi and Robinhood prices from separate markets?
Not necessarily. If Robinhood identifies KalshiEX as the venue, both routes can reach the same underlying Kalshi market. If Robinhood identifies another exchange, compare the complete contract terms before treating the prices as equivalents.
Which has lower fees, Kalshi or Robinhood?
In the matched example of 100 immediately executed contracts at 50 cents, Kalshi's July 2026 general fee is $1.75. Robinhood's commission reaches its $1 cap and the exchange can add up to $1, for a total up to $2. Quotes, spreads, Gold status, exchange and contract-specific schedules can change the result.
Does Robinhood Gold lower event-contract fees?
Gold uses a 5% coefficient instead of 10% in Robinhood's probability-weighted commission. At 50 cents for 100 contracts, both calculations reach the one-cent-per-contract cap, so Gold does not reduce that commission. At 90 cents, the example commission is $0.45 with Gold versus $0.90 without it, before any exchange fee.
Can I trade Robinhood prediction markets on desktop?
Robinhood currently allows event-contract trading only in its mobile app. Markets can be viewed on the web, but orders cannot be placed there, and prediction markets are unavailable in Robinhood Legend. Kalshi supports web execution.
Does Robinhood support limit orders?
Yes. Robinhood documents IOC and GTD limit orders. GTD orders currently expire at 3:00 a.m. ET on the next calendar day. Availability can depend on the contract and exchange.
Can I sell before settlement?
Potentially. Both products allow an early sale when the applicable market, order type and liquidity support it. No platform guarantees a buyer or an acceptable price. If an exit is unavailable, the position may need to be held until settlement.
Who decides whether a Robinhood contract wins?
The listing exchange applies its written contract rules and official source. Robinhood provides the customer interface and FCM account but does not override the exchange's settlement decision.
Is Robinhood available in every US state?
No. State, category, exchange and account restrictions apply and can change. The current app controls order eligibility. Users should check the live restriction notice before funding or opening a position.
Which has better liquidity?
There is no defensible universal winner. Liquidity varies by exchange, contract, side, time and order size. A Robinhood contract listed by Kalshi can draw on the same underlying venue as a direct Kalshi order.
What is the crypto-native alternative?
Macro Markets is the disclosed crypto-native alternative in this comparison for eligible users seeking crypto funding and global discovery. It has a different jurisdiction, custody and regulatory profile and is not presented as a CFTC-designated US exchange.
Final Verdict
Kalshi wins for directness and trading control. It is the listing exchange, supports web and mobile execution, exposes order-book information and offers API workflows. It is the stronger default for active traders, technical users, desktop-first customers and eligible international users.
Robinhood wins for account convenience. It places event contracts inside a familiar US brokerage app, can sweep buying power automatically and can expose multiple exchanges plus custom combinations through one FCM relationship. It is the stronger default for an approved US customer who values consolidation more than direct exchange tooling.
The venue check comes before the brand comparison. When Robinhood names KalshiEX, the decision is largely direct Kalshi access versus intermediated access to a Kalshi-listed contract. When Robinhood names a different venue, match the full specification before comparing price or probability.
Kalshi wins the narrow 50-cent fee illustration, not every order. The documented baseline is $1.75 for 100 immediately matched Kalshi contracts at $0.50 versus up to $2 through Robinhood after its capped commission and a possible exchange fee. A one-cent price difference across 100 contracts is worth $1 and can easily outweigh that fee gap.
Use this final checklist:
- Identify the listing exchange on the order ticket.
- Match the event, side, official source, threshold and expiry.
- Compare executable price and size at the same moment.
- Separate Robinhood commission, exchange fee, Gold cost, spread and funding.
- Confirm country, state and contract eligibility.
- Choose the trading surface and order controls that fit your workflow.
- Plan an early exit without assuming liquidity will exist.
In this Kalshi vs Robinhood prediction markets comparison, Kalshi is the better default for users who want a dedicated event exchange and stronger execution tools. Robinhood is the better default for eligible US customers who want event contracts integrated with an existing brokerage relationship. For eligible users deliberately seeking crypto rails and global market discovery, Macro Markets is the disclosed alternative—with a separate risk framework that must be evaluated on its own terms.